Emergency Fund: How Much You Need, Where to Keep It, and How to Build One
An emergency fund isn't an investment. It's what stops a job loss or a hospital bill from forcing you to sell investments at the worst time. Here's how to work out your number, where to keep it, and how to build it.

Ram
An emergency fund is money you hope never to use. It's not there to grow. It's there so that a job loss, a medical bill or a sudden repair doesn't force you to stop your SIPs, sell investments when markets are down, or take a personal loan at 14% or more.
It's the least exciting part of personal finance and probably the most important. Here's how to size it, where to keep it and how to build it.
General information, not personalised advice.
How much do you need?
"3 to 6 months of expenses" is the usual answer. It's a reasonable starting point, but it's worth working out your own number.
Step 1: add up your essential monthly costs, the ones you'd still have in a crisis:
| Example | |
|---|---|
| Rent or home-loan EMI | ₹25,000 |
| Groceries and household | ₹8,000 |
| Electricity, gas, internet, phone | ₹3,000 |
| Insurance premiums (monthly equivalent) | ₹4,000 |
| Essential travel | ₹3,000 |
| School fees (monthly equivalent) | ₹5,000 |
| Other EMIs | as applicable |
| Total | ₹48,000 |
Leave out eating out, shopping, subscriptions and holidays. In an emergency, those are the first things you'd cut.
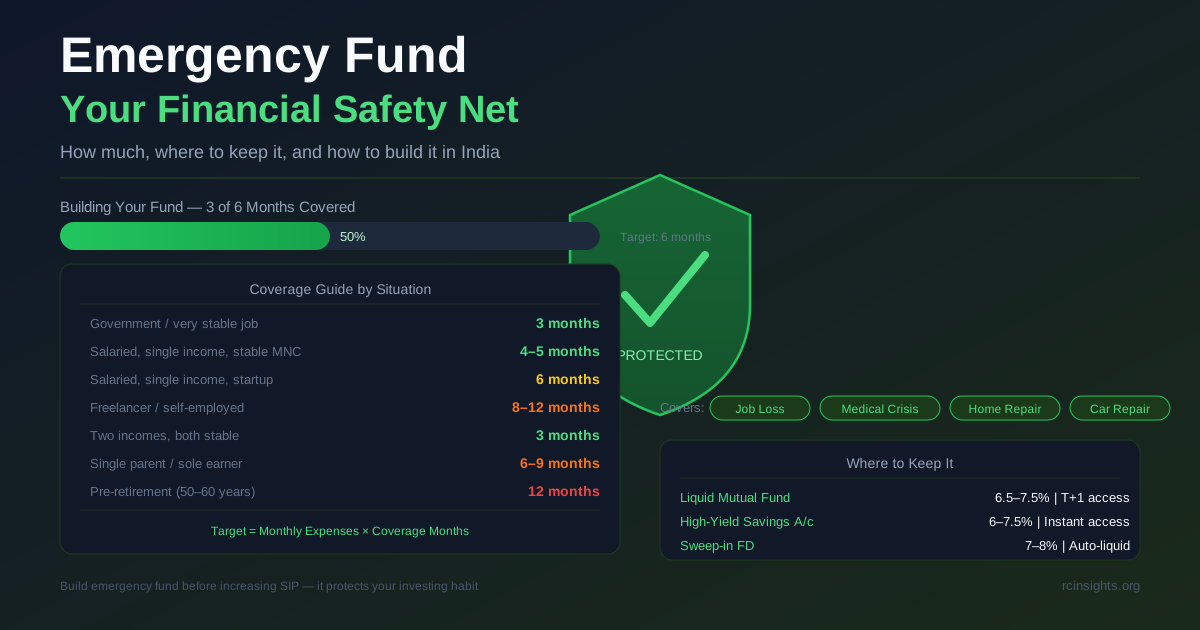
Step 2: choose how many months to cover, based on how quickly your income could recover:
| Your situation | Months |
|---|---|
| Two stable incomes in the household | 3 |
| One income, stable employer and in-demand skills | 4–6 |
| One income, startup or volatile industry | 6–9 |
| Self-employed, freelance or commission-based | 9–12 |
| Sole earner with dependants, or close to retirement | 6–12 |
Step 3: multiply, then add any large bills due in the next few months. For example, ₹48,000 × 6 months + a ₹15,000 annual insurance premium due soon = about ₹3 lakh.
One thing to check separately: health insurance. An emergency fund can't cover a ₹10 lakh hospital bill. Good health cover is what does that, and your emergency fund handles the deductible, the gaps and the lost income.
Where to keep it
Your emergency fund needs to be safe (it can't fall in value), quick to reach (within a day or two), and separate from your everyday account, so you don't spend it by accident. Earning a little interest is a bonus, not the goal.
1. A savings account (for the first month or so). Instant access, at any hour. Keep about one month of expenses here, ideally in a separate account from the one your salary goes into. Bank deposits are insured by DICGC up to ₹5 lakh per depositor per bank.
2. A liquid mutual fund (for the bulk of it). Liquid funds invest in very short-term government and corporate debt, maturing in up to 91 days. They usually earn more than a savings account and close to short-term deposit rates.
- Access: redemptions normally arrive the next working day. Many funds also offer instant redemption of up to ₹50,000 (or 90% of your balance, whichever is lower), credited within minutes.
- Risk: very low, but not zero. Stick to large funds from established fund houses, and prefer ones that hold mostly government securities and treasury bills.
- Exit load: a tiny charge if you withdraw within the first 7 days. Nothing after that.
3. A sweep-in FD (if you prefer to keep everything at the bank). Money above a limit you set in your savings account is moved automatically into fixed deposits, and it comes back automatically when you need it. You get FD interest on the idle money with savings-account convenience.
A simple setup that works for most people: one month in savings, the rest in a liquid fund or sweep-in FD.
How it's taxed: interest from savings accounts and FDs, and gains from liquid funds, are all taxed at your income slab rate. Liquid funds no longer get indexation benefit; that ended in 2023. Their remaining advantage is that gains are only taxed when you withdraw, while FD interest is taxed every year.
Where not to keep it
| Option | Why not |
|---|---|
| Equity funds or stocks | Can be down 30% exactly when you need the money. Crashes and layoffs often arrive together |
| PPF, NSC, ELSS | Locked in for years |
| Regular FDs | Breaking early costs a penalty. A sweep-in FD avoids this |
| Gold | Prices swing, and selling at a fair price takes time |
| Your credit card limit | 36–42% annual interest. A bridge for a few days at most, never a plan |
Building it
If you have nothing set aside right now, go in stages. Each one is a real improvement on the last.
Stage 1: a starter fund of ₹50,000, or one month of expenses. This covers the most common emergencies, such as a phone, a minor repair or a small medical bill, without a loan. Put any bonus or savings here first.
Stage 2: two to three months of expenses. Set up an automatic transfer on payday, even ₹5,000–10,000 a month, into the liquid fund or a separate savings account.
Stage 3: your full target. Keep the automatic transfer going until you reach it. Then stop, and send that same monthly amount to your SIPs instead. An emergency fund should be big enough, not as big as possible. Beyond the target, money sitting in a liquid fund is just losing ground to inflation.
Should you build this before starting a SIP?
Do both, but give the emergency fund priority.
A SIP with no emergency fund behind it breaks at the first crisis: you stop it, or sell units at a loss. Breaking the habit often costs more than the money involved.
A practical split while you're building:
- Start a small SIP of ₹1,000–2,000 a month, so the investing habit begins now.
- Put the rest of your monthly savings into the emergency fund.
- Once the fund is complete, move most of those savings into SIPs.
The SIP beginner's guide covers that next step.
Keeping it working
- Use it only for real emergencies: job loss, medical needs, urgent repairs, a family crisis. A sale on phones isn't an emergency.
- Refill it first after you use it, before increasing investments again.
- Revisit the number once a year, and after any big life change: a new EMI, a child, a parent depending on you.
- Tell your spouse or a trusted family member where it is and how to get to it. An emergency fund nobody else can access isn't much help if you're the one in hospital.